
e-Invoice Implementation in Malaysia: Timeline & Exemptions
Understand the current LHDN implementation phases, the updated RM3 million exemption threshold, and what Malaysian SMEs should prepare for MyInvois.
Check implementation timeline
RM3 million: the updated e-Invoice exemption threshold
LHDN updated its implementation timeline on 30 August 2026. Taxpayers with annual turnover or revenue below RM3 million are exempt from mandatory e-Invoice implementation, subject to the conditions in its guidelines. The previous RM500,000 threshold on older articles is no longer current.
e-Invoice implementation timeline in Malaysia
| Annual turnover / revenue | Implementation date |
|---|---|
| More than RM100 million | 1 August 2024 |
| More than RM25 million up to RM100 million | 1 January 2025 |
| More than RM5 million up to RM25 million | 1 July 2025 |
| Up to RM5 million, where mandatory implementation applies | 1 January 2026 |
| Below RM3 million and meeting exemption conditions | Exempt from mandatory implementation |
Source: LHDN e-Invoice implementation timeline, updated 30 August 2026. The exemption takes precedence for eligible taxpayers.
Three MSME exemption checks
Check annual turnover
Confirm the relevant annual turnover or revenue and applicable year of assessment under LHDN’s rules.
Review group relationships
Check non-individual shareholders, holding companies, subsidiaries and related-company or joint-venture relationships against LHDN’s conditions.
Review mandatory status
If the business’s mandatory implementation year has already been determined, falling below RM3 million later does not automatically restore the exemption.
Get your invoicing workflow ready
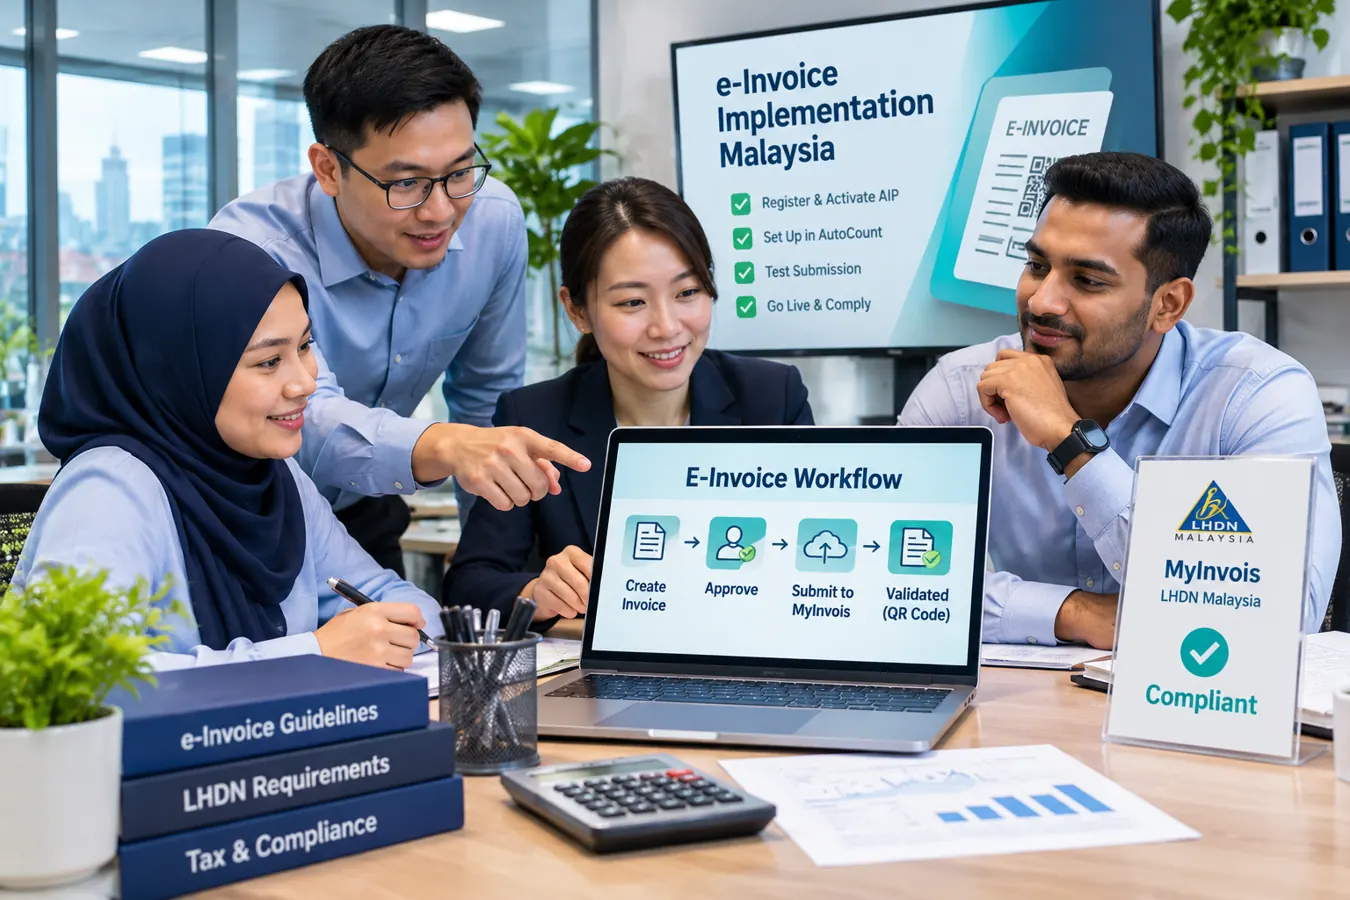
Customer data: Review identification, TIN and contact information needed for relevant transactions.
Transaction types: Identify B2B, B2C, consolidated and self-billed scenarios that apply to your business.
Validation: Plan how invoices are transmitted and validated via MyInvois, then retained for reconciliation.
Use genuine software workflows rather than relying on manually typed invoices and inconsistent records.
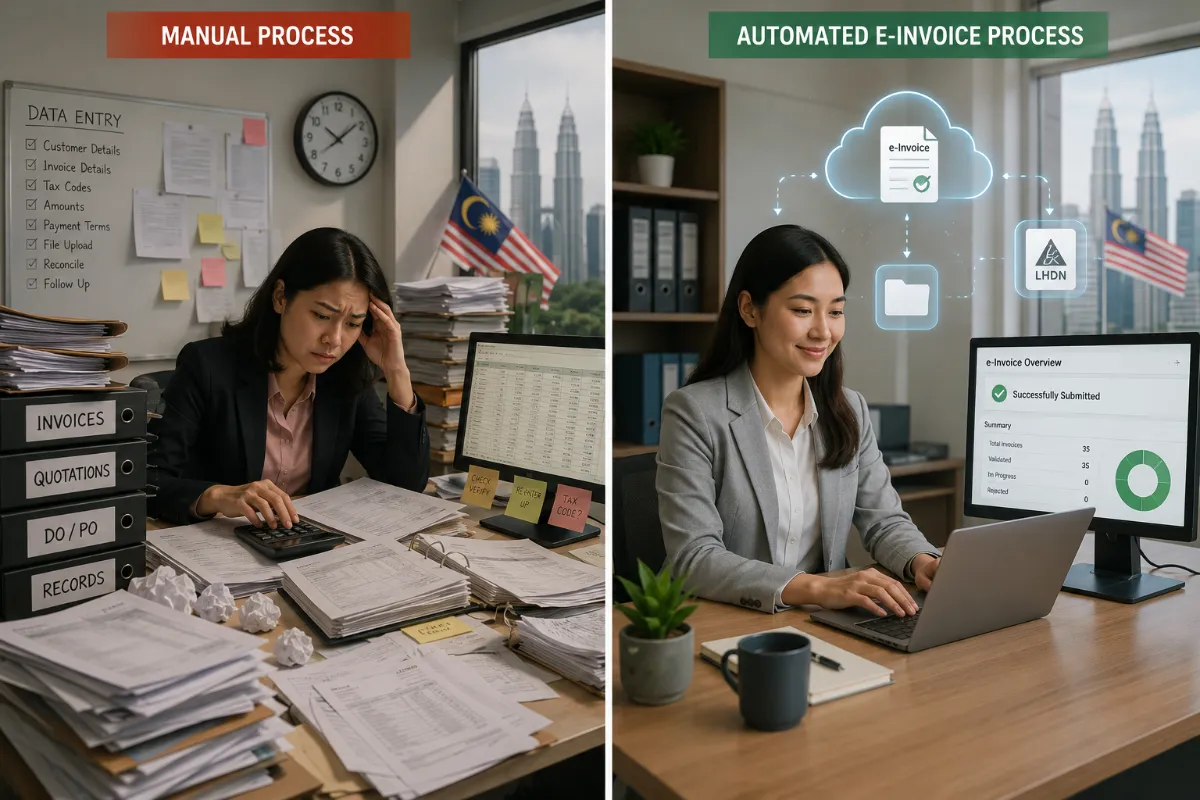
Four steps to prepare for e-Invoice implementation
Confirm applicability
Verify your revenue, relationships and mandatory implementation year.
Check transaction data
Review buyer details, tax fields and transaction classifications.
Test the workflow
Trial invoice creation, validation, cancellation and correction paths.
Reconcile records
Match accounting and validated e-Invoice records on an ongoing basis.
Malaysia e-Invoice implementation FAQs
Are all businesses below RM3 million exempt?
Not necessarily. The current LHDN timeline provides the below-RM3 million exemption, but related-company, ownership and existing implementation obligations can affect eligibility. Review the current official guideline and FAQ.
Does a drop in revenue automatically remove an existing e-Invoice obligation?
No. LHDN’s FAQ says an exemption is not granted again merely because annual revenue later falls below RM3 million once the mandatory implementation year has been determined.
Must an eligible exempt business issue consolidated or self-billed e-Invoices?
LHDN’s FAQ states that eligible exempt taxpayers are not required to issue consolidated or self-billed e-Invoices, although voluntary adoption is encouraged. Other parties may still need transaction details for their own obligations.
Where should businesses confirm the latest rules?
Check the LHDN implementation timeline, e-Invoice Guideline and General FAQ before making a compliance decision.
Prepare your AutoCount e-Invoice workflow
Read the AutoCount e-Invoice user guide or explore AutoCount Cloud Accounting for related workflows.
Explore AutoCount Cloud AccountingImplementation starts with clarity
Know whether the mandate applies, prepare accurate records and select a consistent submission workflow.
References from LHDN
Implementation Timeline (updated 30 August 2026) · e-Invoice Guideline v4.8 and Specific Guideline v4.9 · LHDN General FAQ
General information only. For group structures, prior implementation decisions and exceptions, confirm your position against the latest LHDN guidance or with a qualified adviser.